
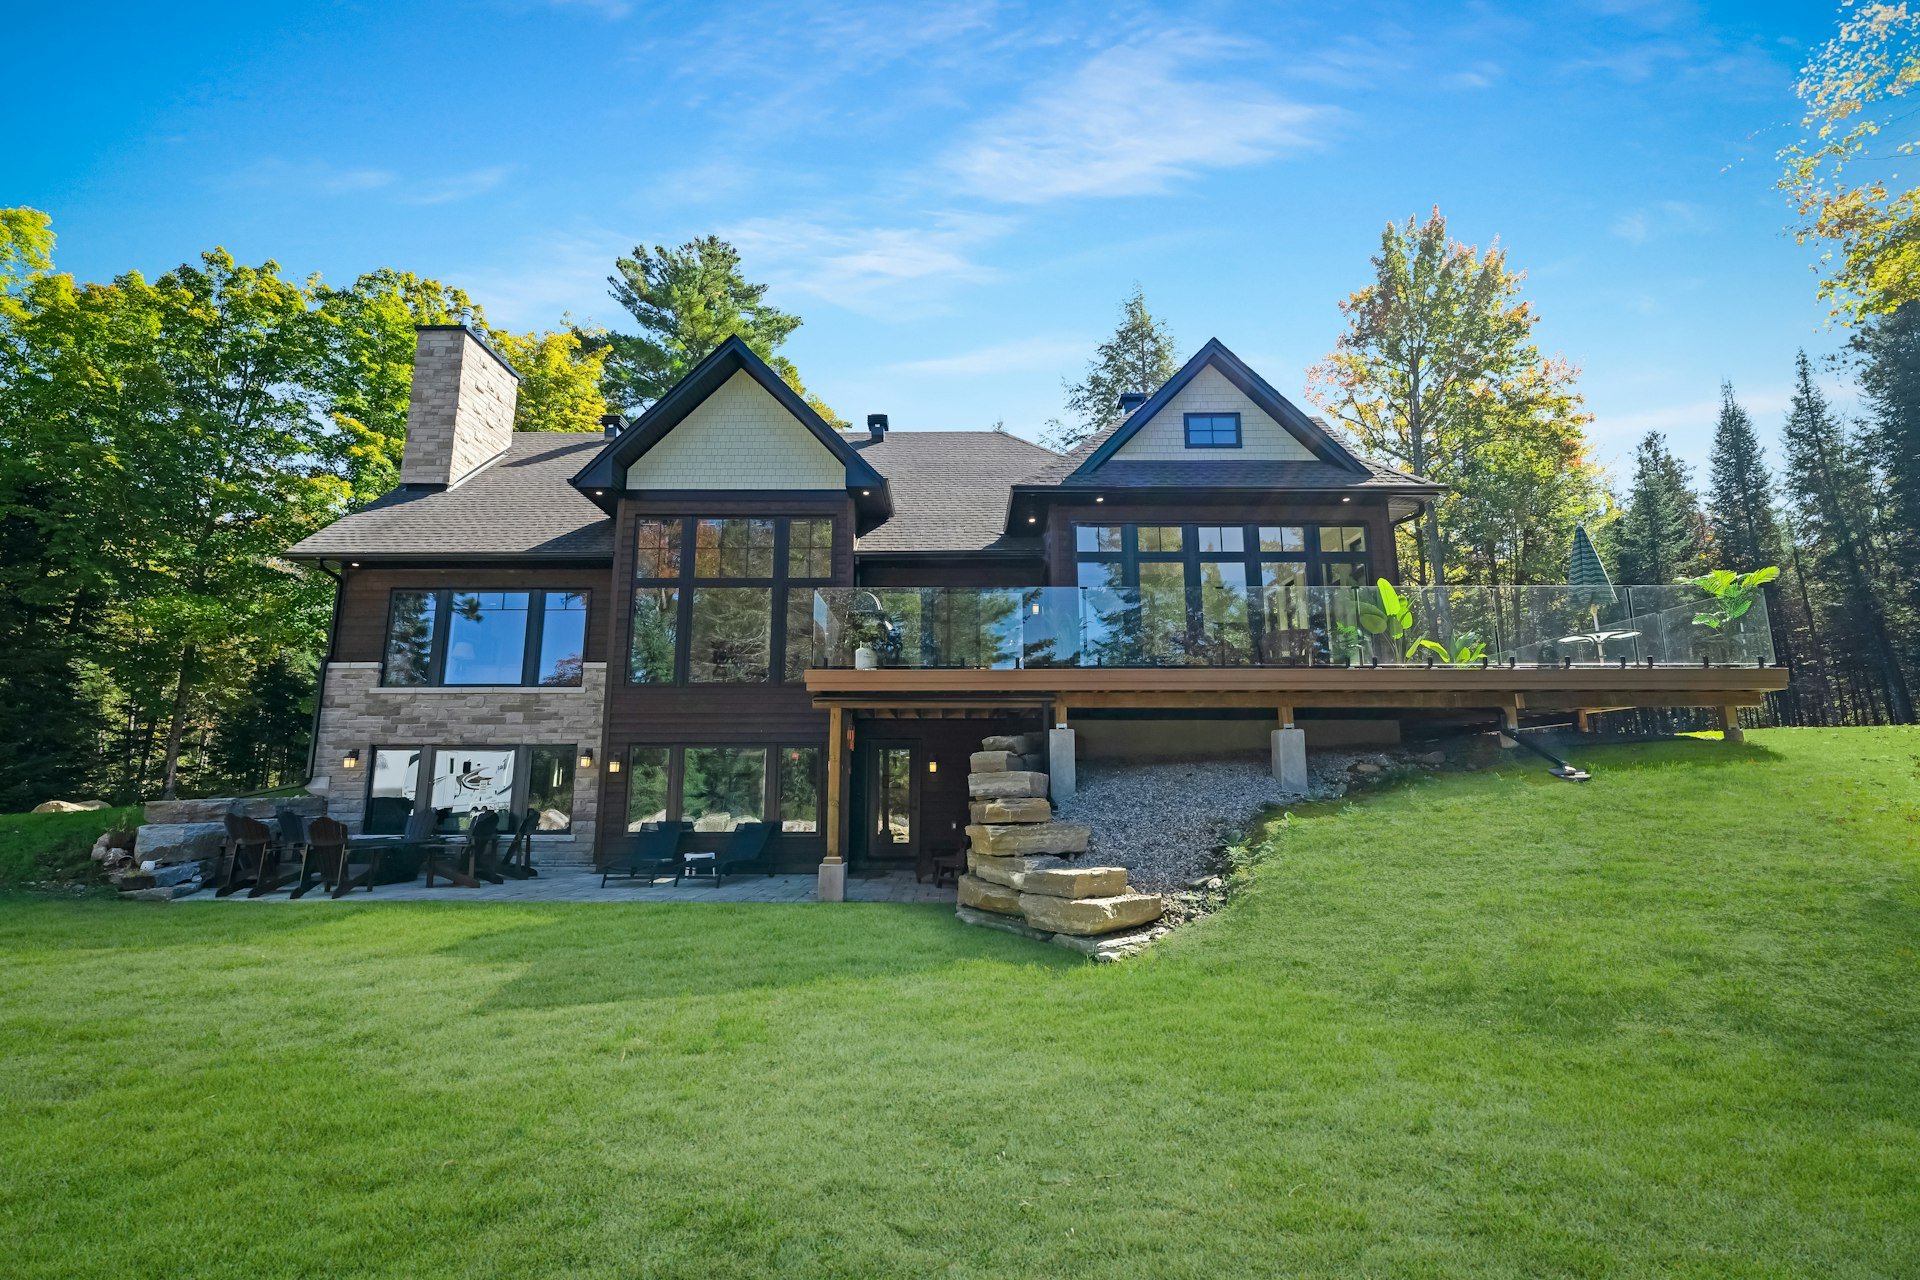
Market value does not tell the whole insurance story
A home can require specialized attention because of its rebuild cost, custom construction, architectural detail, location, systems or the property kept inside it. Insurers do not all use the same threshold or underwriting rules for a high-value home.
The goal is not simply to choose a larger limit. It is to document the property accurately and understand how the policy would respond to a partial or total covered loss.
Build a defensible rebuilding estimate
Custom millwork, stone, historic details, imported finishes, complex mechanical systems, detached structures and professional fees can make reconstruction different from ordinary construction. The insurer may request a detailed replacement-cost estimate, appraisal, inspection, photographs or plans.
Review what the policy includes for demolition, debris removal, by-law changes, landscaping and additional living expenses. Ask what conditions apply to replacement-cost coverage and whether the insurer requires updated valuations or completion of risk-control recommendations.
Treat collections and special items separately
Home-policy limits for jewellery, fine art, wine, antiques and other special property may not reflect the collection’s value or the way it should be settled. A review can consider appraisals, scheduled items, blanket collection limits, deductibles and coverage while an item is away from the home.
Related guidance is available for jewellery, fine art and wine collections. Coverage availability and appraisal requirements vary by insurer.
Consider the household and liability exposure
Tell the advisor about pools, watercraft, domestic employees, frequent guests, home offices, events, renovations, vacant periods and any property held through a trust or corporation. Confirm how vehicles, secondary residences and personal umbrella or excess-liability options fit with the home policy.
Security, water-leak detection, backup power and monitored fire protection may be underwriting considerations. Do not install or represent a protective system solely for insurance purposes without confirming the insurer’s requirements.
Prepare for a detailed review
Gather the current policy, recent valuation or appraisal, construction and renovation details, photos, claims history, mortgage information and inventories for important collections. Contact Westoak to discuss which insurers and policy structures may be available for the property.